Two bedrooms in downtown San Jose
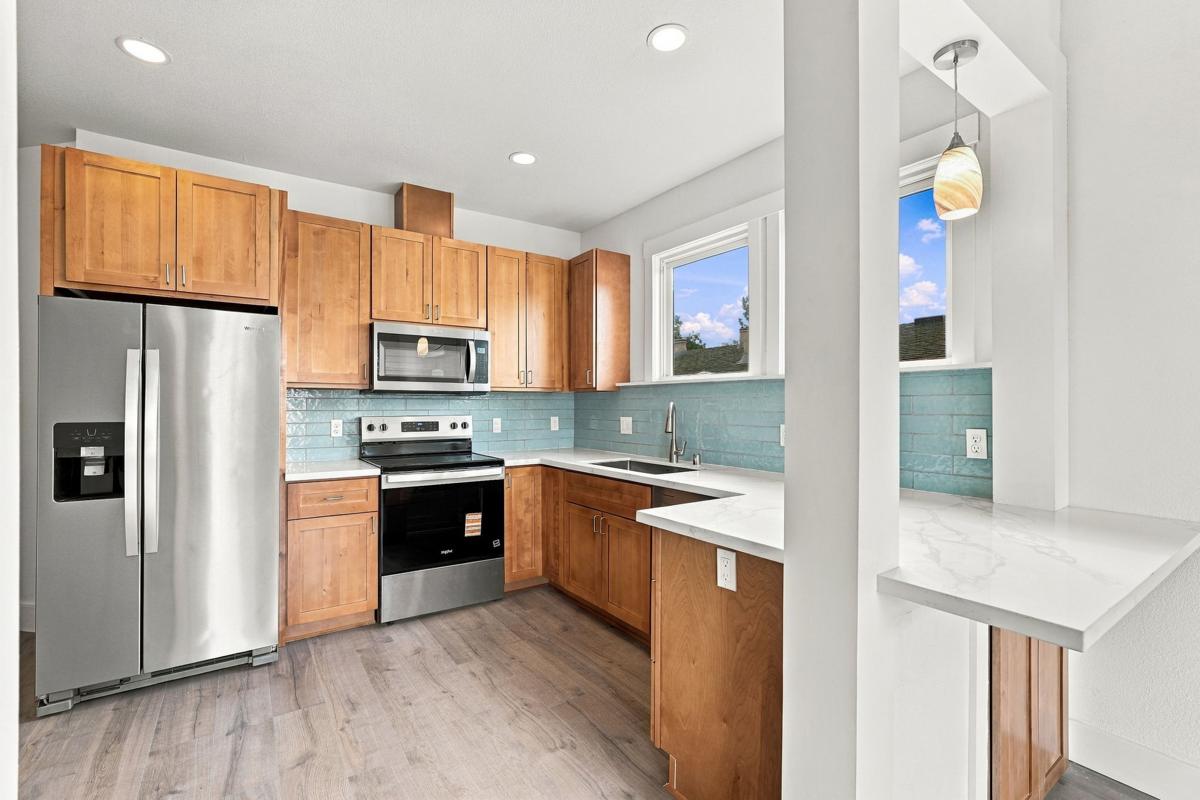
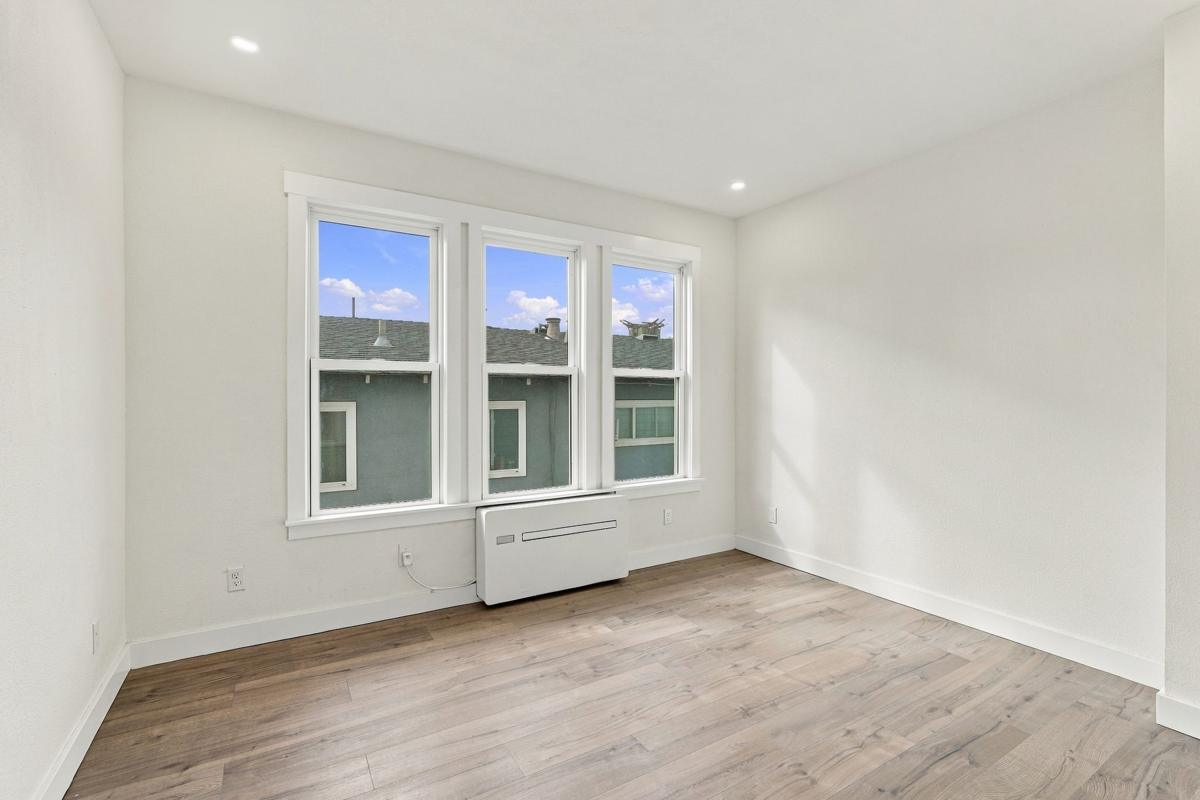
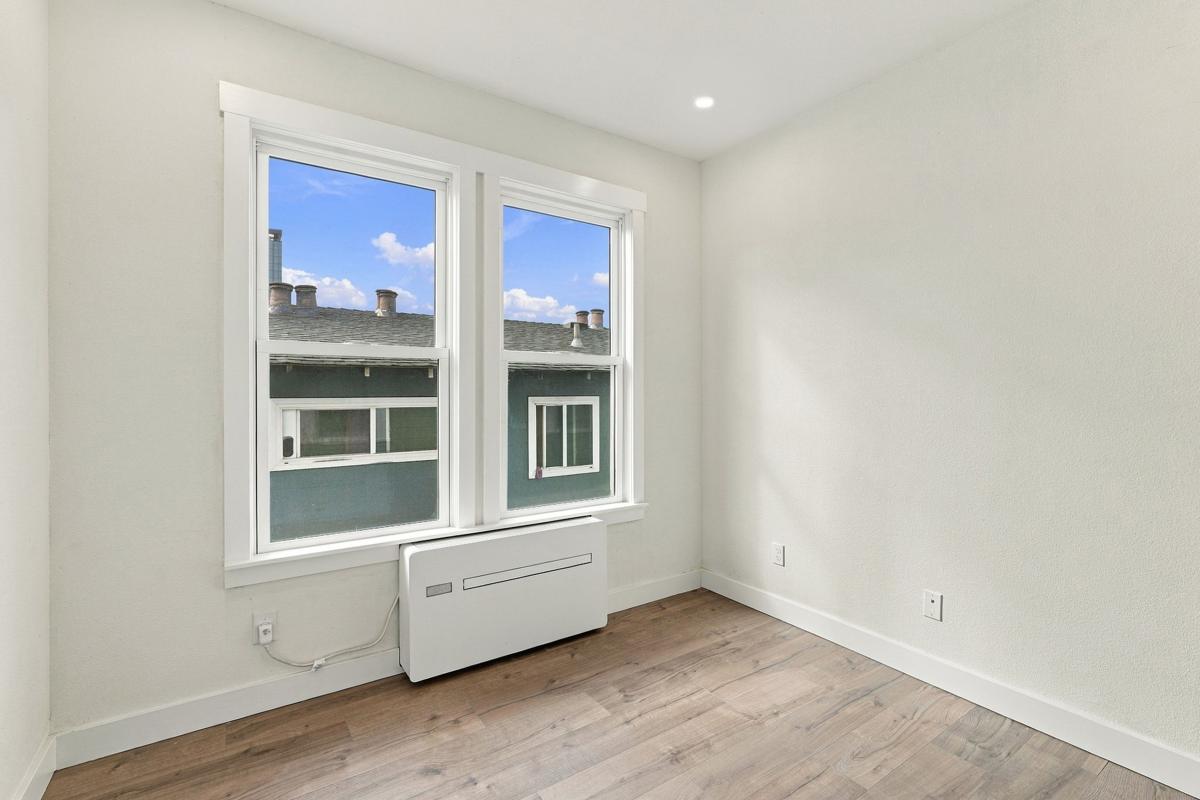
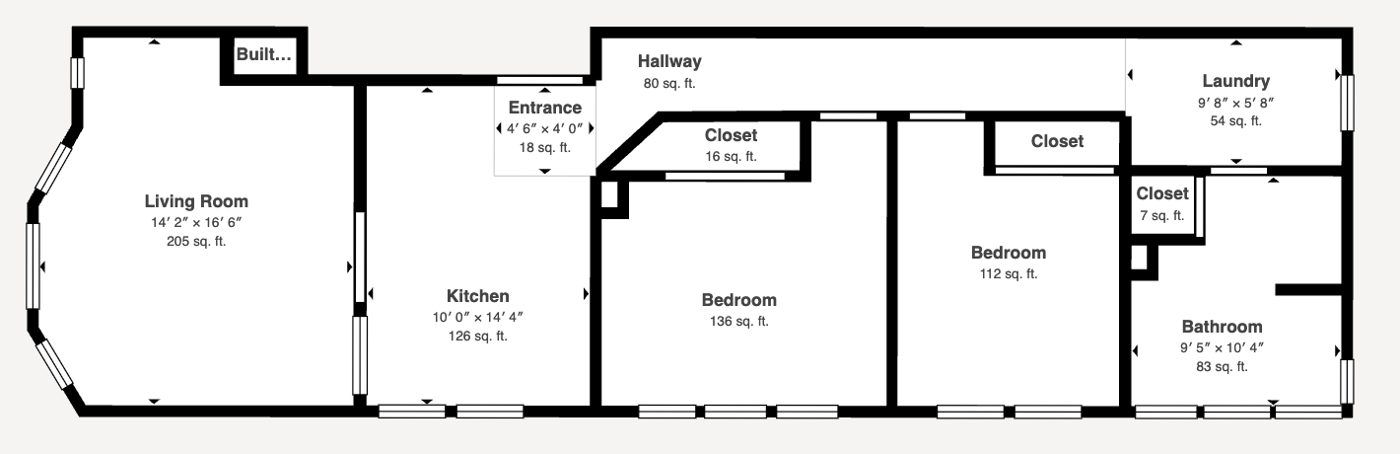
A single-level unit of about 1,031 square feet in a classic two-story building on East Reed Street, near downtown San Jose and San José State.
- 2 bedrooms, 1 full bathroom
- Upstairs unit, about 1,031 sq ft on one level
- Living room with a bay window
- Built-in hutch and bookshelves
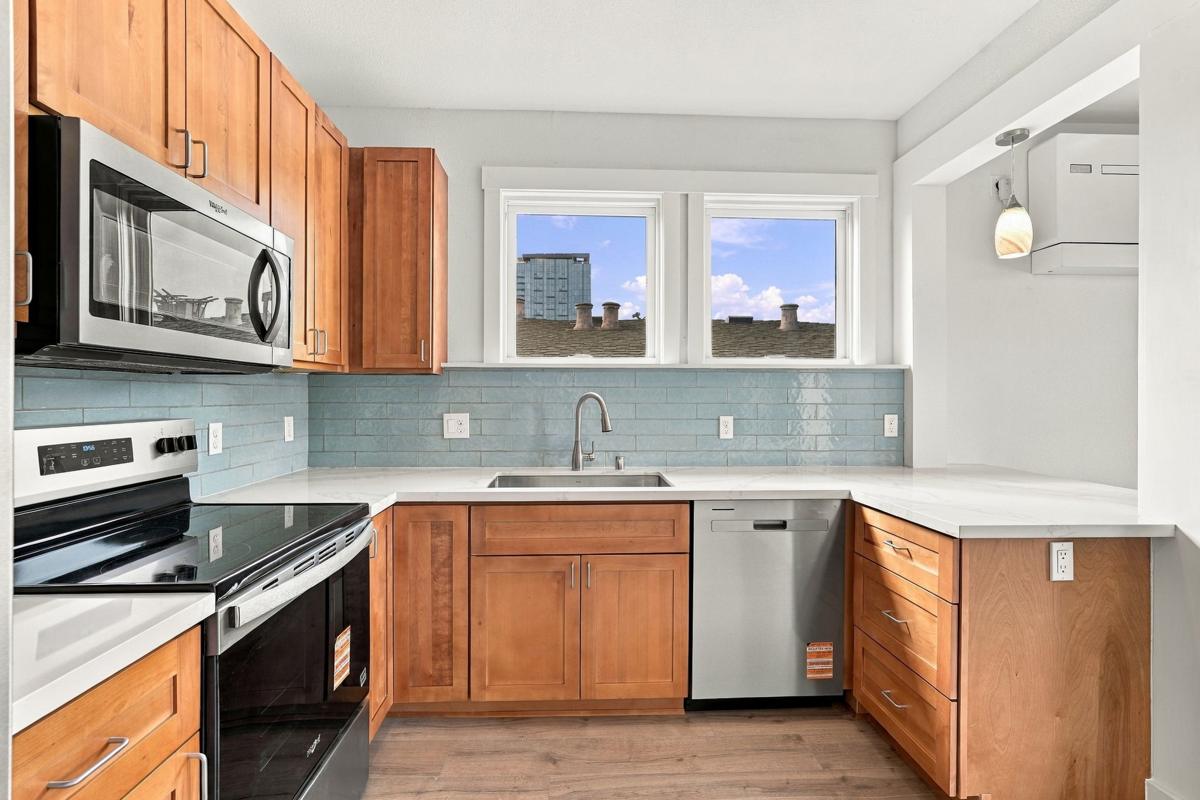
- Kitchen with stainless appliances and glass tile backsplash
- Separate laundry room inside the unit
- No on-site parking. Parking is not guaranteed
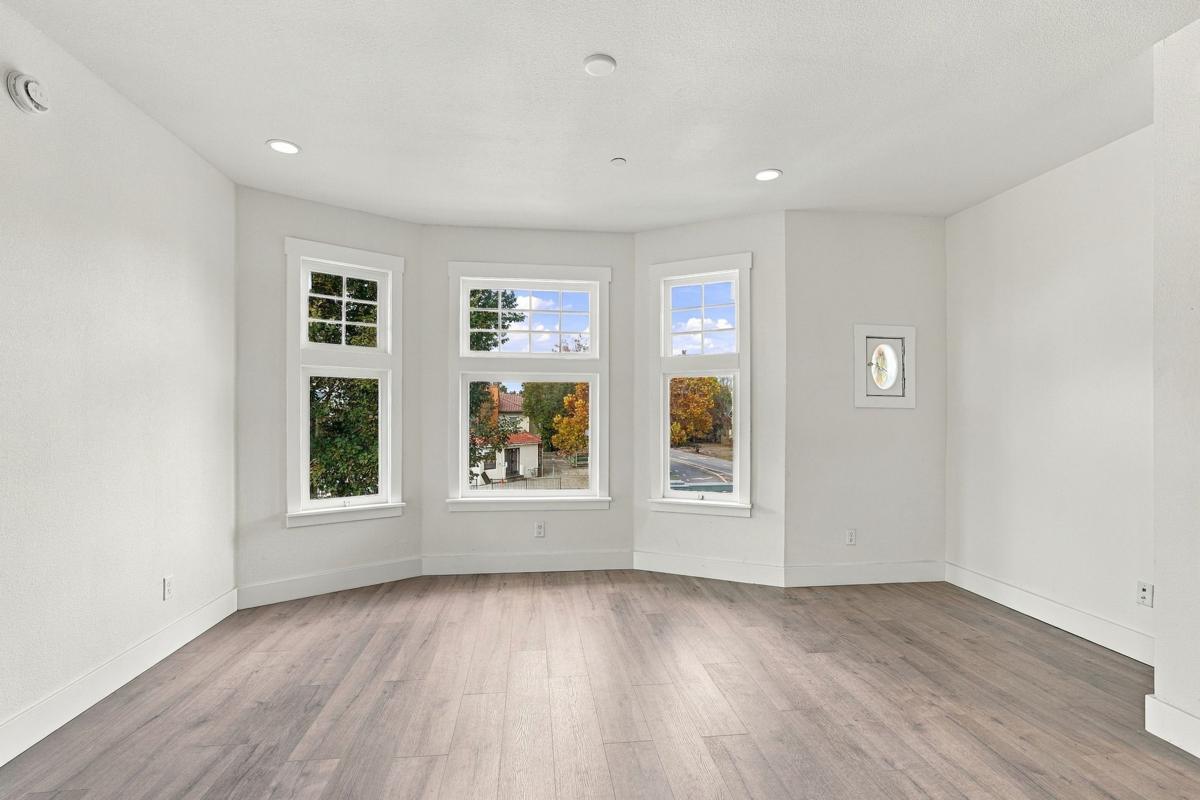
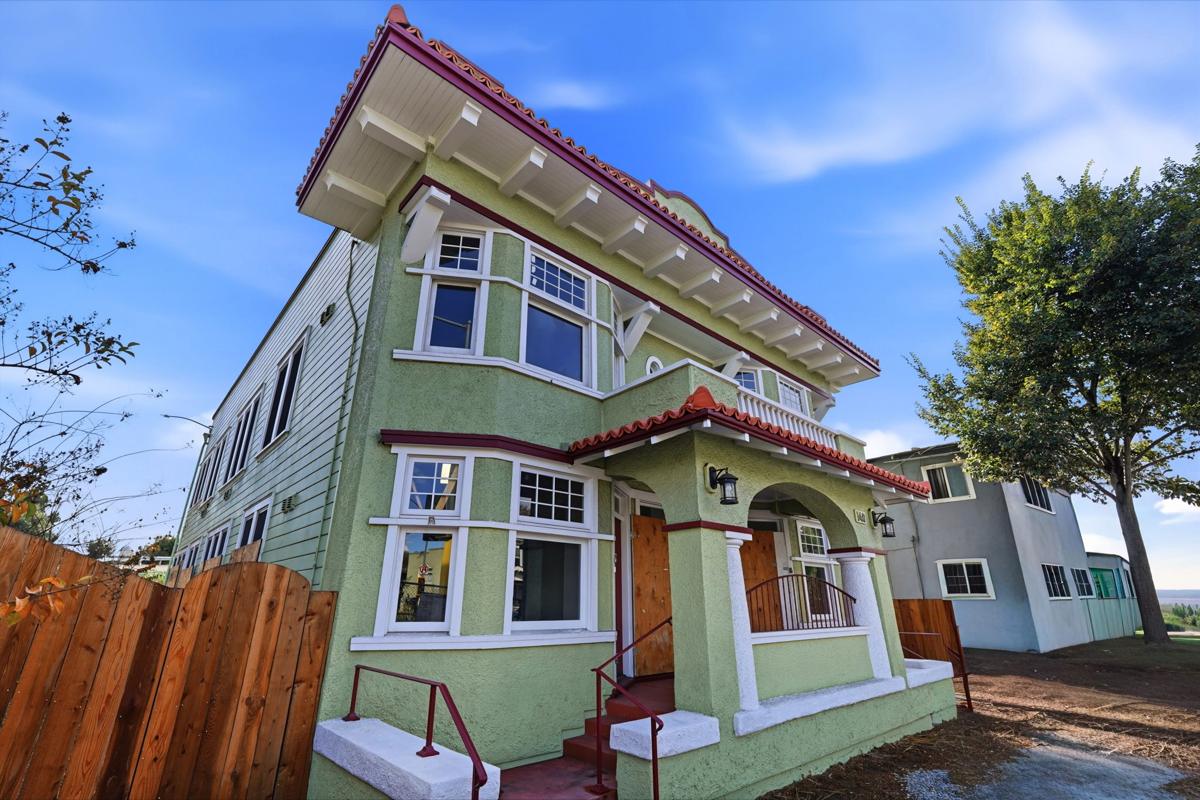
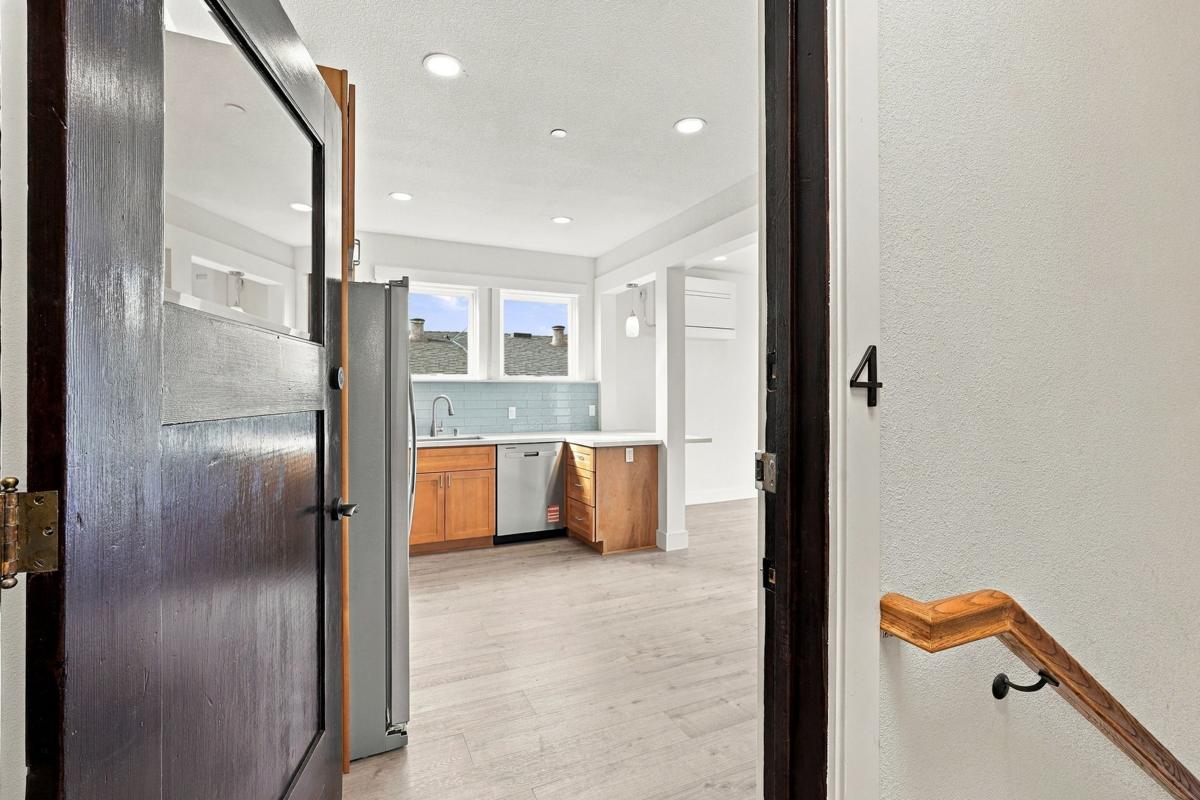
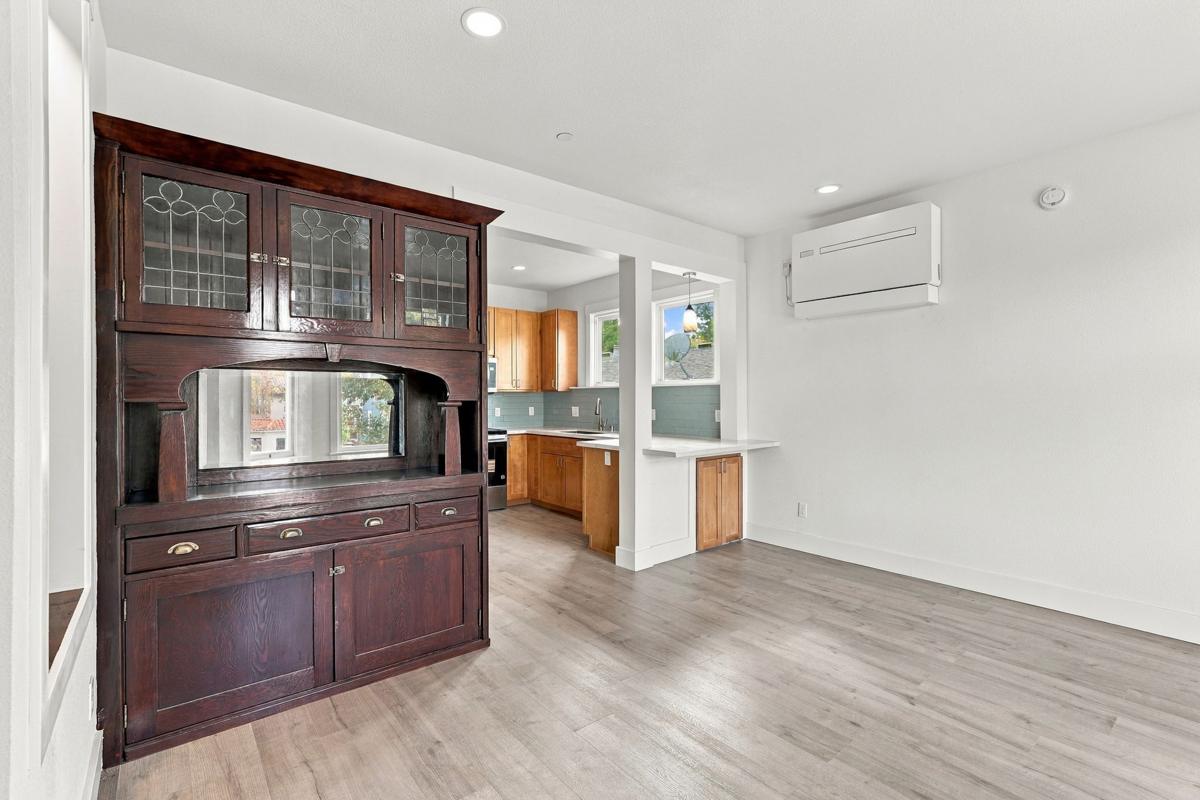
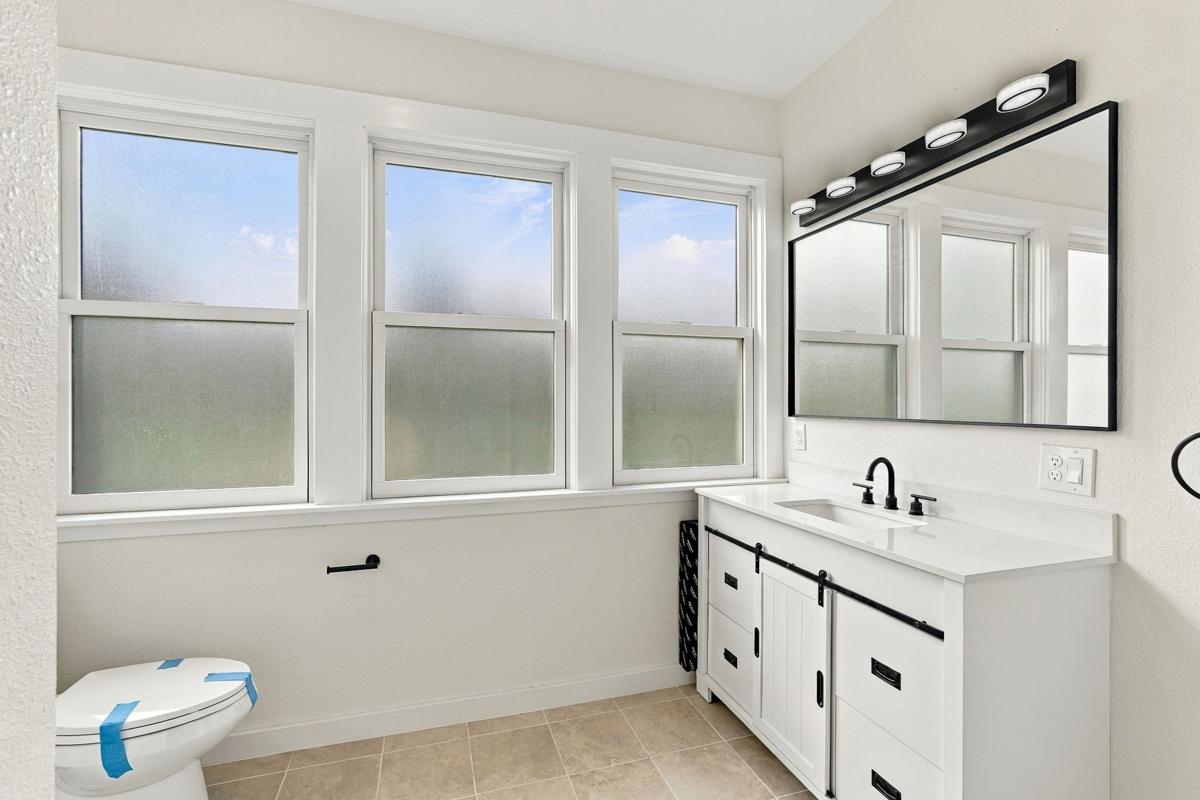
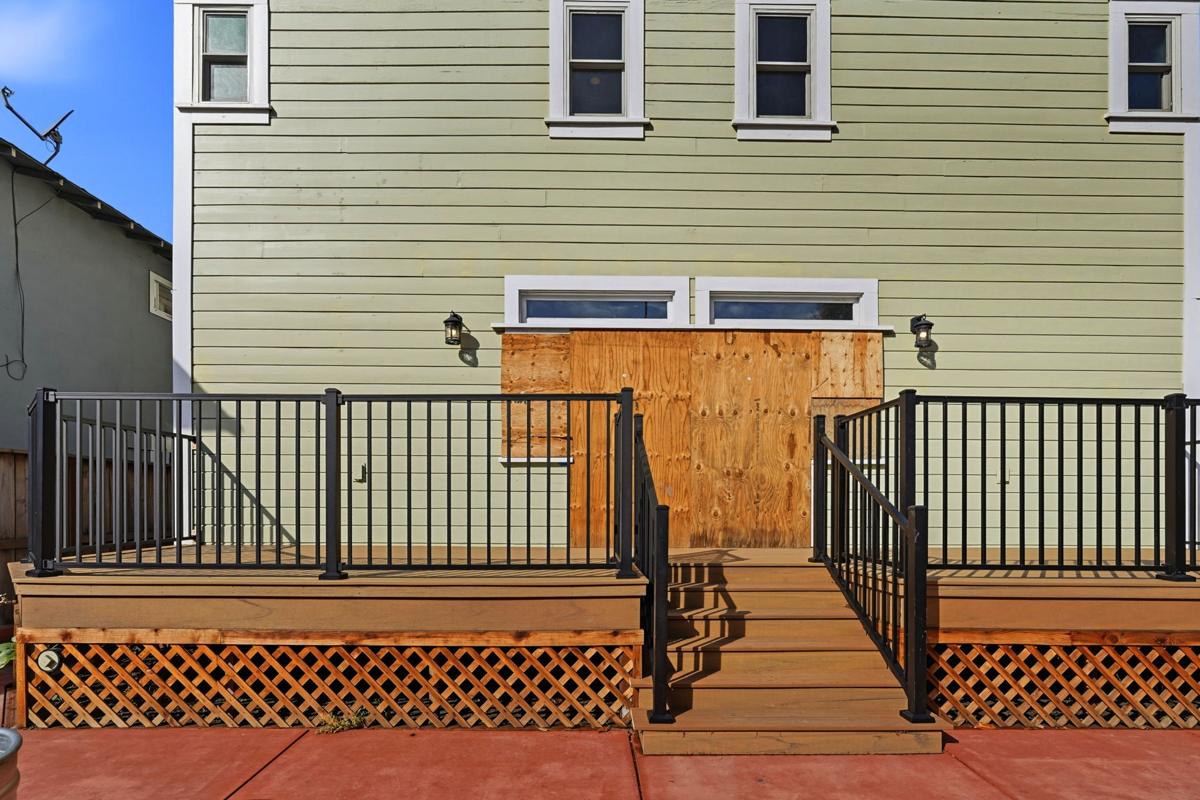
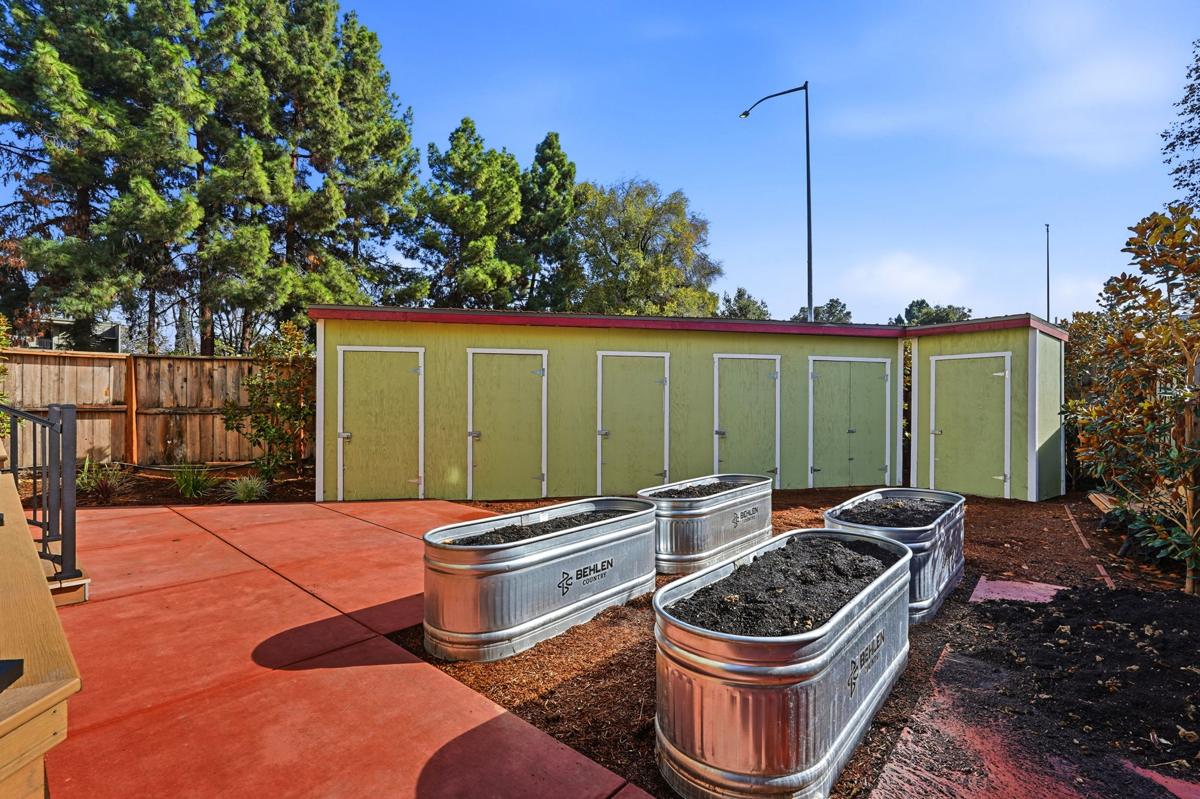
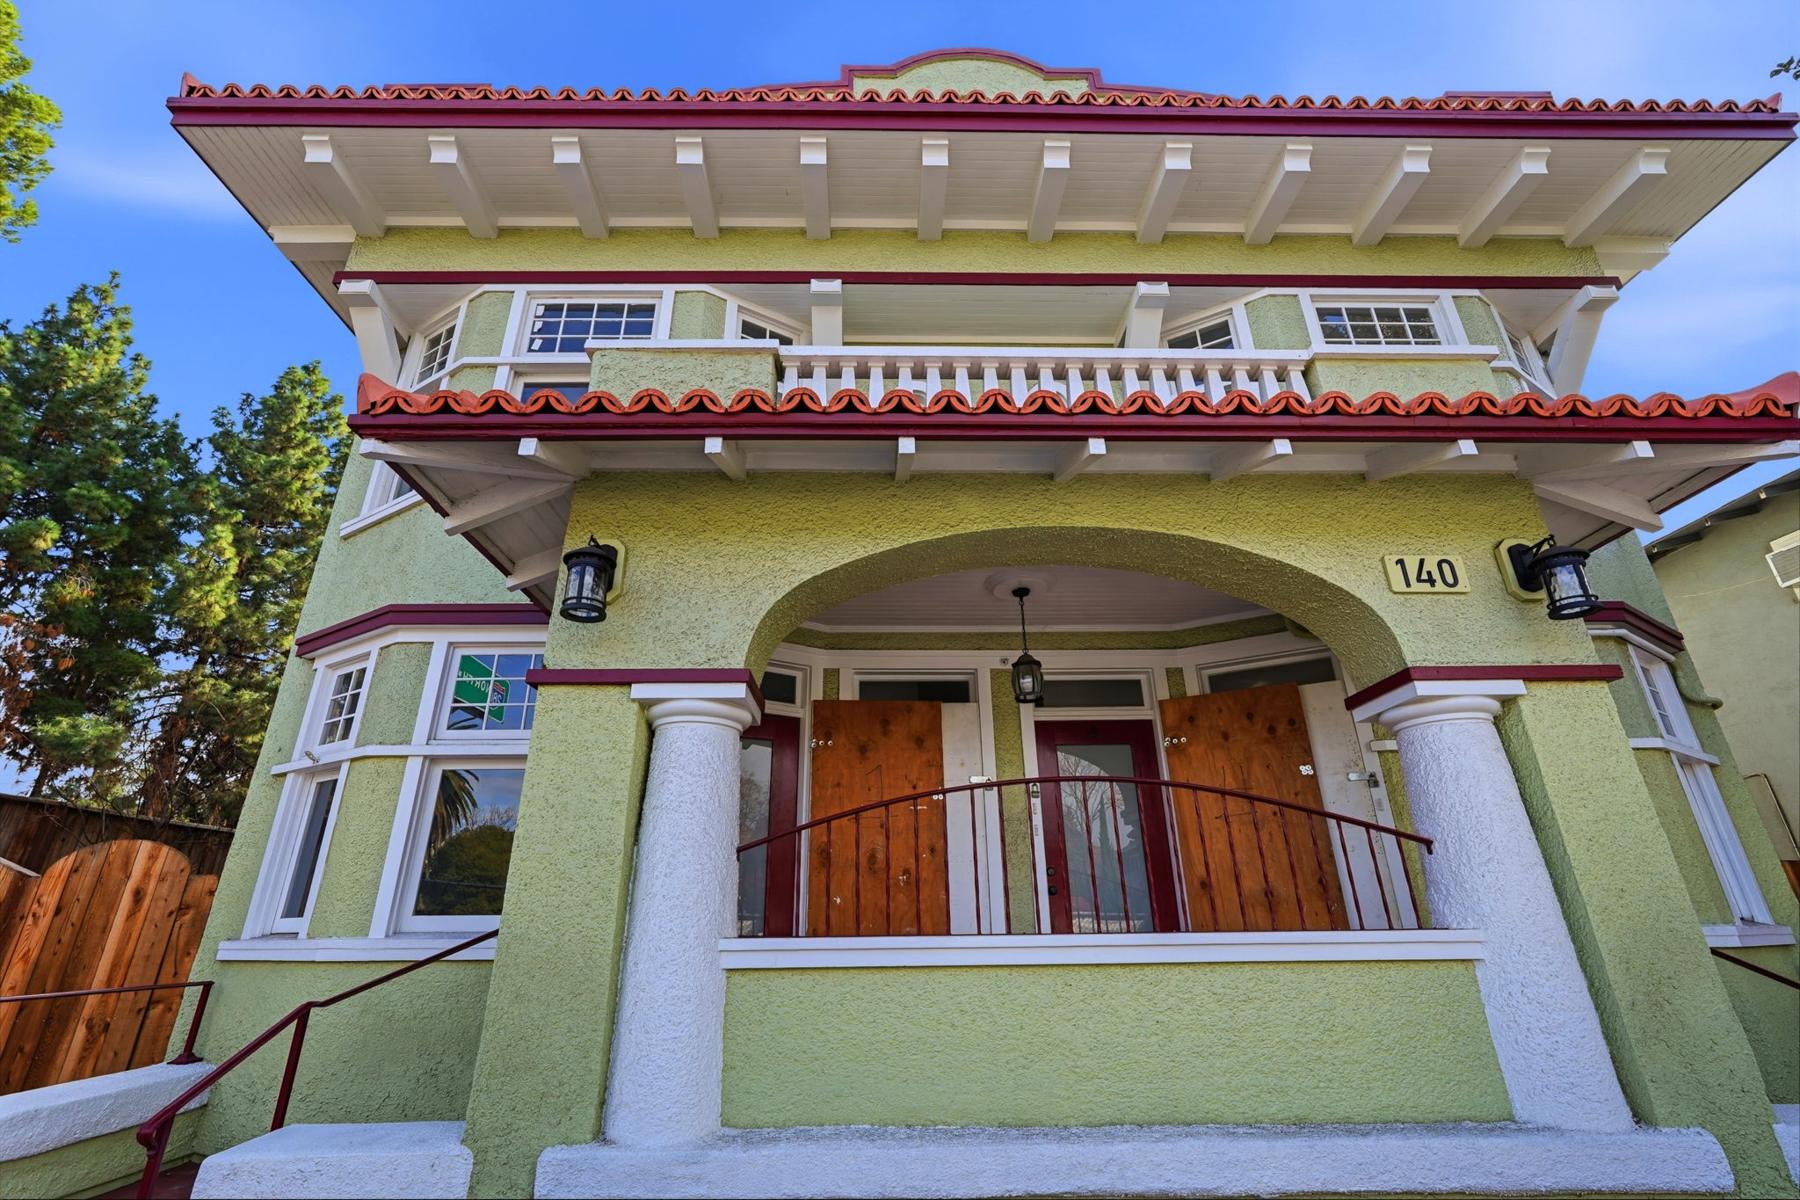
This is not a regular listing
Unit 4 is sold through Habitat for Humanity at an affordable price. Buyers have to meet Habitat's income, credit and program rules, and Habitat approves every buyer. Start by reading who qualifies below. Then request the application on Habitat's 4th and Reed page.
- Price
- $374,337
- Down payment
- None
- Mortgage
- 5.5% fixed, 30-year*Example rate, subject to change
- Closing costs
- About $10,000Gift funds allowed
- HOA dues
- About $500 / monthFinal amount pending insurance
- Household size
- 1 to 4 people
- Income range
- 30% to 50% of area medianSee the limits below
- Sweat equity
- 250 hours
Household income range
Your household's total gross annual income, before taxes, must fall between 30% and 50% of the area median income (AMI) for your household size. Count everyone who will live in the home.
Households of 5 to 8 are shown for reference. This unit is limited to households of 1 to 4 people.
See all 2026 Santa Clara County income limits
Swipe the table sideways to see larger households.
| AMI | 1 person | 2 people | 3 people | 4 people | 5 people | 6 people | 7 people | 8 people |
|---|---|---|---|---|---|---|---|---|
| 120% AMI | $172,620 | $197,280 | $221,940 | $246,600 | $266,328 | $286,056 | $305,784 | $325,512 |
| 110% AMI | $158,235 | $180,840 | $203,445 | $226,050 | $244,134 | $262,218 | $280,302 | $298,386 |
| 100% AMI | $143,850 | $164,400 | $184,950 | $205,500 | $221,940 | $238,380 | $254,820 | $271,260 |
| 80% AMI | $113,700 | $129,950 | $146,200 | $162,400 | $175,400 | $188,400 | $201,400 | $214,400 |
| 65% AMI | $93,503 | $106,860 | $120,218 | $133,575 | $144,261 | $154,947 | $165,633 | $176,319 |
| 50% AMI Maximum for this unit | $71,950 | $82,200 | $92,500 | $102,750 | $111,000 | $119,200 | $127,450 | $135,650 |
| 30% AMI Minimum for this unit | $43,200 | $49,350 | $55,500 | $61,650 | $66,600 | $71,550 | $76,450 | $81,400 |
Rows from 50% to 120% are Habitat's 2026 HUD chart for Santa Clara County. The 30% row is the state housing department's 2026 extremely-low-income limit. This unit is for households of 1 to 4 earning between the highlighted rows. Limits usually change once a year.
At least $4,300 a monthHabitat estimates a household needs at least $4,300 a month in gross income, about $51,600 a year, to afford the payments. Total monthly housing cost, including HOA dues, must also stay at or under 35% of gross monthly income.
4 people maximumThis unit is limited to households of 1 to 4 people. A household of 5 or more is not eligible for this home.
Where the numbers come fromMaximums are the 50% AMI figures on Habitat's 2026 Santa Clara County chart and its 4th and Reed requirements sheet. Minimums are the state's 2026 extremely-low-income (30% AMI) limits. Both usually change once a year.
Could your household qualify?
A rough first look, not an approval. Habitat makes every eligibility decision from a complete application.
Example figures are filled in. Enter your own household's numbers.
Who does not qualify
Most of these are firm program rules. Items marked Fix first are not permanent: clear them up, then apply.
| Requirement | Not eligible if |
|---|---|
| Household income | Under 30% or over 50% of AMI for your household size, or more than 4 people in the household. |
| Housing cost | Total monthly housing cost, including HOA dues, would be more than 35% of gross monthly income. |
| First-time buyer | Anyone on title owned a home in the last 3 years and no HUD exception applies. A spouse's ownership counts. |
| Credit history | A foreclosure or bankruptcy in the last 3 years (counted from the discharge date), or more than 2 late payments in the last 12 months. |
| Credit accounts | Fewer than 3 accounts open 12+ months in good standing for each applicant, and no alternative credit in your own name with 12 months of on-time payments. No exceptions. |
| Debt | Debts on your credit report plus the estimated mortgage payment are more than 43% of gross income. Deferred student loans are counted. |
| Open credit itemsFix first | Open collections, charge-offs (profit and loss accounts), past-due balances, judgments or liens of any size. Clear them, then apply. |
| Residency | No one on title has permanent U.S. legal residency, or proof is missing for anyone on title. |
| Household | Household members have lived together less than 6 months. |
| Partnership | You can't commit to 250 sweat-equity hours or the required orientation. |
| Use of the home | You plan to rent the home out. It must be your primary residence. |
| ApplicationFix first | Unsigned, undated or missing documents. Incomplete applications are not reviewed. |
Six steps from interest to keys
Habitat handles completed, approved applications strictly first come, first served. A complete application the first time keeps your place in line.
Request the application
Fill out the short form on Habitat's 4th and Reed page. Habitat emails you the 4th and Reed application and the orientation video.
Complete and sign it
Fill in every section, sign and date it (DocuSign, Adobe Sign or ink) and attach every document it asks for.
Upload it
Use the 4th and Reed upload link in Habitat's email. Mail works too but is slower.
Habitat review
Usually under 10 business days. Allow up to 14 around holidays.
County, contract, lender
Santa Clara County reviews the file and may ask for more documents. Then the purchase agreement, then approval with Habitat's partner lender.
Sweat equity and closing
Complete 250 sweat-equity hours and close. Plan on about $10,000 in closing costs.
Request the 4th and Reed application
Documents to send with your application
Habitat only reviews complete applications. If anything below is missing, or the application isn't fully filled out and signed, it won't be processed and may be denied.
Credit report fee
Identity and residency
Household and housing
Income, for everyone 18 or older
Bank accounts and assets, for everyone 18 or older
Frequently asked questions
Income and household
Is there a minimum income?
Yes, two of them. Household income has to be at least 30% of the area median for your household size, for example $61,650 for a household of 4. Habitat also estimates a household needs at least $4,300 a month in gross income (about $51,600 a year) to afford the payments. Whichever is higher applies. Your total monthly housing cost (mortgage, property taxes, insurance and HOA dues) must also stay at or under 35% of your gross monthly income.
Who counts in my household?
You define your family: one person, a couple, a single parent with children, or extended relatives. Everyone who will live in the home counts, and you must have lived together for at least 6 months before applying.
What counts as income, and how do I prove it?
Gross income before taxes for everyone in the household. Employment isn't required, but all income has to be documented. Everyone 18 or older provides their 3 most recent pay stubs or benefit statements (employment, SSI, EDD, disability, pension), 2 years of federal tax returns, and 2 years of W-2s or 1099s. Anyone 18 or older with no income provides a no-income letter. See the full document checklist.
Our household is 5 people. Can we apply?
Not for this unit. It is limited to households of 1 to 4. Habitat has other homes and programs, so contact them about future opportunities.
Our income is a little over the limit. Is there any flexibility?
No. The 50% AMI limit for your household size is a hard cap for this home.
Credit
What credit score do I need?
There's no minimum score. Habitat looks for no major problems on the report, and checks the credit of everyone who will be on title.
- Three credit accounts per applicant, each open at least 12 months and in good standing.
- Short of three? You can use alternative credit, such as rent or utility payments, but it must be in your name, open for the last 12 months and paid on time. There are no exceptions to this rule.
- No more than 2 late payments in total in the last 12 months.
- Debts on your credit report plus the estimated mortgage payment at 43% of gross income or less. Deferred student loans are included.
I had a bankruptcy or foreclosure. Can I still qualify?
Not if it was in the last 3 years. For a bankruptcy, Habitat counts from the discharge date.
I have a collection account. Am I out?
Not permanently. Open collections, charge-offs (profit and loss accounts), past-due balances, judgments and liens must be cleared before you can move forward, no matter how small. Once they're cleared, you can apply.
Eligibility
What does "first-time buyer" mean here?
Habitat uses HUD's definition: no ownership of a home in the 3 years before this purchase, including a spouse. Exceptions include a single parent who only owned with a former spouse, a displaced homemaker who only owned with a spouse, and someone who only owned a mobile home not on a permanent foundation or a property that couldn't meet building codes.
Do I need to be a U.S. citizen?
Everyone on title needs proof of U.S. legal residency, and at least one person on title needs proof of permanent legal residency, such as citizenship or a green card.
Can I rent it out later?
No. The home must be your primary residence.
What is the resale restriction?
The home carries a resale restriction of at least 65 years. During that time:
- If you sell, Habitat has the first right to buy the home.
- The home is resold to another moderate-income family at an affordable price.
- Any refinance must be approved by Habitat.
Costs and the loan
Do I really need no down payment?
Correct. There's no down payment. You will need about $10,000 for closing costs, which covers setting up the tax and insurance account, the credit report, appraisal, title and insurance.
Can family help with closing costs?
Yes, gift funds are allowed. Ask your donors to wait until Habitat confirms you qualify and the purchase agreement is signed before they send any money.
What will my monthly payment be?
Habitat and its partner lender will provide the final monthly estimate, including principal, interest, property taxes, insurance and HOA dues. The HOA is expected to be about $500 a month once the building's insurance is final. Your total housing cost must stay at or under 35% of your gross income.
Can I use my own lender?
The loan for this home comes through Habitat's partner lender. The 5.5% fixed, 30-year rate on this page is an example only. The actual rate and terms are set by the lender at loan approval and may change.
Is parking included?
No. The building has no on-site parking, and parking is not guaranteed at this time.
- Habitat is working on arranging spaces in a parking garage about a 7-minute walk from the home. If that's arranged, Habitat plans to pay for the first year.
- Habitat is also asking the city for permit parking on the street. That is still being pursued and isn't guaranteed.
If you need a parking space, plan for the possibility that neither option is available.
The process
What is sweat equity?
250 hours of hands-on work helping Habitat build homes. Construction is currently in Hayward. If travel is a hardship, tell Habitat, because the location can be flexible. Friends and family can contribute some of the hours, and Habitat makes reasonable accommodations for health and disability.
How long does approval take?
Habitat's review usually takes under 10 business days (allow 14 around holidays). After that come Santa Clara County's review, the purchase agreement and lender approval.
If several buyers qualify, who gets the home?
It's strictly first come, first served, based on complete, approved applications. An incomplete application isn't reviewed and doesn't hold a place in line.
Do I need to take a homebuyer class?
You need Habitat's orientation for full approval. Habitat sends the orientation video with the application, or you can watch it here. Habitat also offers a separate online HUD first-time homebuyer course ($99 per person). Habitat doesn't require it, but many other below-market and down-payment assistance programs do.
Can I tour the home first?
Yes. Showings are by appointment. Contact Tuan Tran to schedule.
Can I work with my own real estate agent?
Yes. Your agent can contact Tuan Tran for details.
Ready to apply, or want to see it?
Habitat for Humanity East Bay/Silicon Valley
Request the 4th and Reed application and ask eligibility questions.
Request the applicationTuan D. Tran
800 W El Camino Real #180, Mountain View, CA 94040